When it comes to securing a mortgage, many people focus solely on their credit scores.
While credit scores are undeniably important, they are just one piece of a larger puzzle. Understanding the other factors that affect mortgage qualification can help you improve your chances of success and achieve your homeownership goals.
Let’s explore the various elements that lenders consider when evaluating mortgage applications beyond just credit scores. The mortgage qualification process involves multiple layers of scrutiny, and being aware of these can empower you to take the right steps.
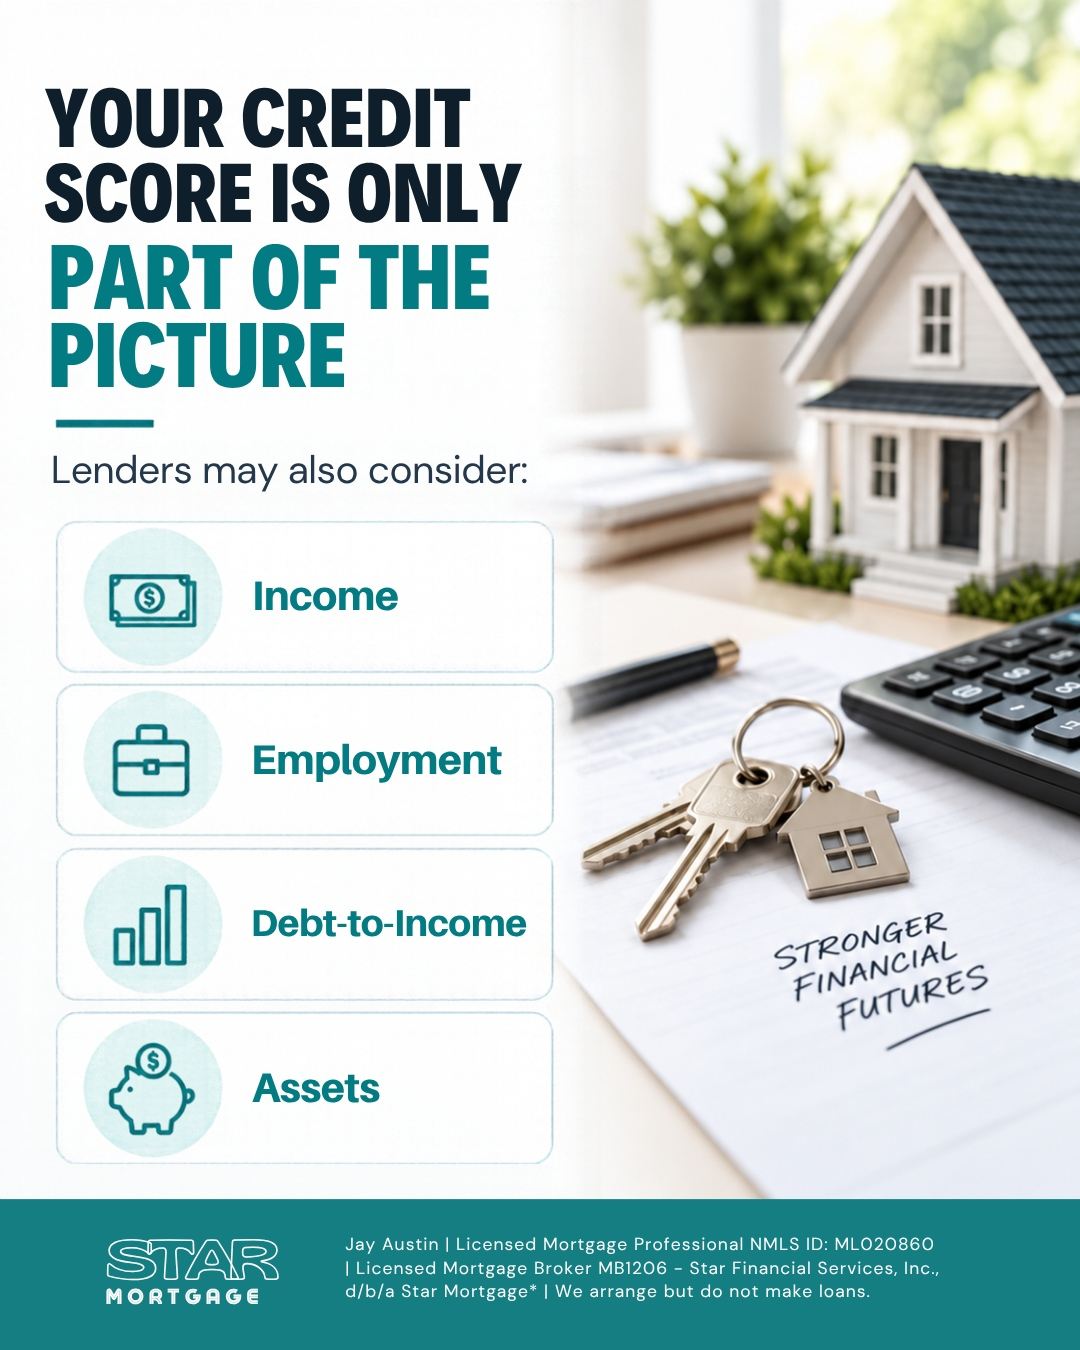
First, let's discuss income. Lenders want to know that you have a reliable source of income to cover your mortgage payments. They will typically ask for pay stubs, W-2s, and tax returns to verify your earnings. A stable job history enhances your application. If you've been with the same employer for a significant amount of time, that can work in your favor. However, if you're self-employed or have an irregular income, it's crucial to document your earnings carefully to show lenders that you have the capability to make monthly payments.
Next, debt-to-income ratio (DTI) is a critical component in the mortgage qualification process. This ratio compares your monthly debts to your gross monthly income. Lenders usually prefer a DTI of 43% or lower. To calculate your DTI, add up all your monthly debt payments, including credit cards, car loans, student loans, and any other financial obligations. Then take that number and divide it by your gross monthly income. Reducing your DTI can strengthen your application. Consider paying down existing debts or avoiding new debts as you prepare to apply for a mortgage.
Another important factor is the amount of your down payment. The more money you can put down upfront, the less risk you pose to the lender. A larger down payment can lower your monthly payments and possibly eliminate the need for private mortgage insurance (PMI). If you're struggling to save for a down payment, look into programs that offer assistance or consider creating a dedicated savings plan to reach your goal.
Assets and reserves also play a role in mortgage qualification. Lenders want to see that you have some savings in the bank, even after your down payment. Having reserves demonstrates your ability to cover mortgage payments in case of emergencies or job loss. Keep track of your assets, including savings accounts, investments, and any other resources that can be liquidated if necessary.
Your employment history is another key factor. Stability is essential. If you have frequent job changes, lenders may view you as a greater risk. Demonstrating a consistent employment record can help alleviate concerns. If you are a recent graduate or just starting in the workforce, be prepared to explain your career trajectory and future earning potential.
Credit history, while linked to your credit score, deserves special attention. Lenders will assess your credit report to look for any red flags, such as missed payments, bankruptcies, or collections. It's a good idea to review your credit report before applying for a mortgage. This way, you can address any discrepancies or old debts that might hurt your chances. Work on improving your credit habits, such as making timely payments and reducing your credit utilization, to enhance your overall credit profile.
Another consideration is the type of mortgage you wish to secure. Different loans come with various qualification requirements. For example, FHA loans offer more flexibility with lower credit scores and smaller down payments, making them appealing to first-time homebuyers. On the other hand, conventional loans may require higher credit scores but offer more favorable terms for those who qualify. Familiarize yourself with the types of loans available and how they match your financial situation.
The property type and condition also impact your mortgage qualification. Lenders will want to ensure that the property serves as collateral for the loan. They will conduct an appraisal to assess its value. If the home is in disrepair or located in an area with lower property values, it may complicate the approval process. Be proactive—consider getting a home inspection before you make an offer so you can address any potential issues early.
Documentation is critical throughout the mortgage process. Being organized and having all required documents ready can speed up your application. Prepare a comprehensive file that includes your identification, income verification, employment history, tax documents, bank statements, and any other relevant paperwork. This preparation not only helps your lender but also reduces stress on your part as you navigate through the approval process.
Lastly, consider your long-term financial goals. A mortgage is a significant commitment, and it is important to align your mortgage choice with your overall financial health. Think about how the mortgage fits into your budget and future plans. Will you be able to afford the payments comfortably? Have you factored in property taxes, insurance, and maintenance costs? These elements can impact your financial stability, so take the time to assess them realistically.
Achieving mortgage qualification success isn't just about having a good credit score. It involves understanding and managing various financial factors that contribute to a strong mortgage application. By focusing on income stability, improving your DTI, saving for a down payment, and maintaining a healthy credit history, you can set yourself up for a successful mortgage experience.
If you have specific questions or need personalized guidance tailored to your financial situation, I invite you to reach out and speak with a Star Mortgage Licensed Mortgage Professional. They will provide Sound Advice and be there as your valuable advisor throughout the entire process of purchasing or refinancing a home. Together, we can navigate the complexities of the mortgage process and help you achieve your homeownership dreams.
Call 508 941-5616 to speak with a Licensed Mortgage Professional. If you are in the beginning stages of planning to purchase a home or just need some sound advice, just give us a call 508 941-5616 text or email Advice@StarMortgage.com
Get pre-approved quickly with our SECURE ONLINE Loan Application. It's Quick and Easy and available 24 hours a day - 7 days a week.
Click here: Why the Right Pre-Approval Letter Matters When You Make an Offer to Purchase - Star Mortgage
Sound Advice Topics Sponsored by StarMortgage.com
Now go back to Our Blog Home Page to learn more about all about financing a home Blog - Star Mortgage