When it comes to buying a home, understanding your financing options is one of the most important steps you can take.
Two of the most popular choices for home financing are FHA (Federal Housing Administration) loans and conventional loans. Both types of loans have their own benefits and drawbacks, and knowing how they differ can help you make the best decision for your unique situation.
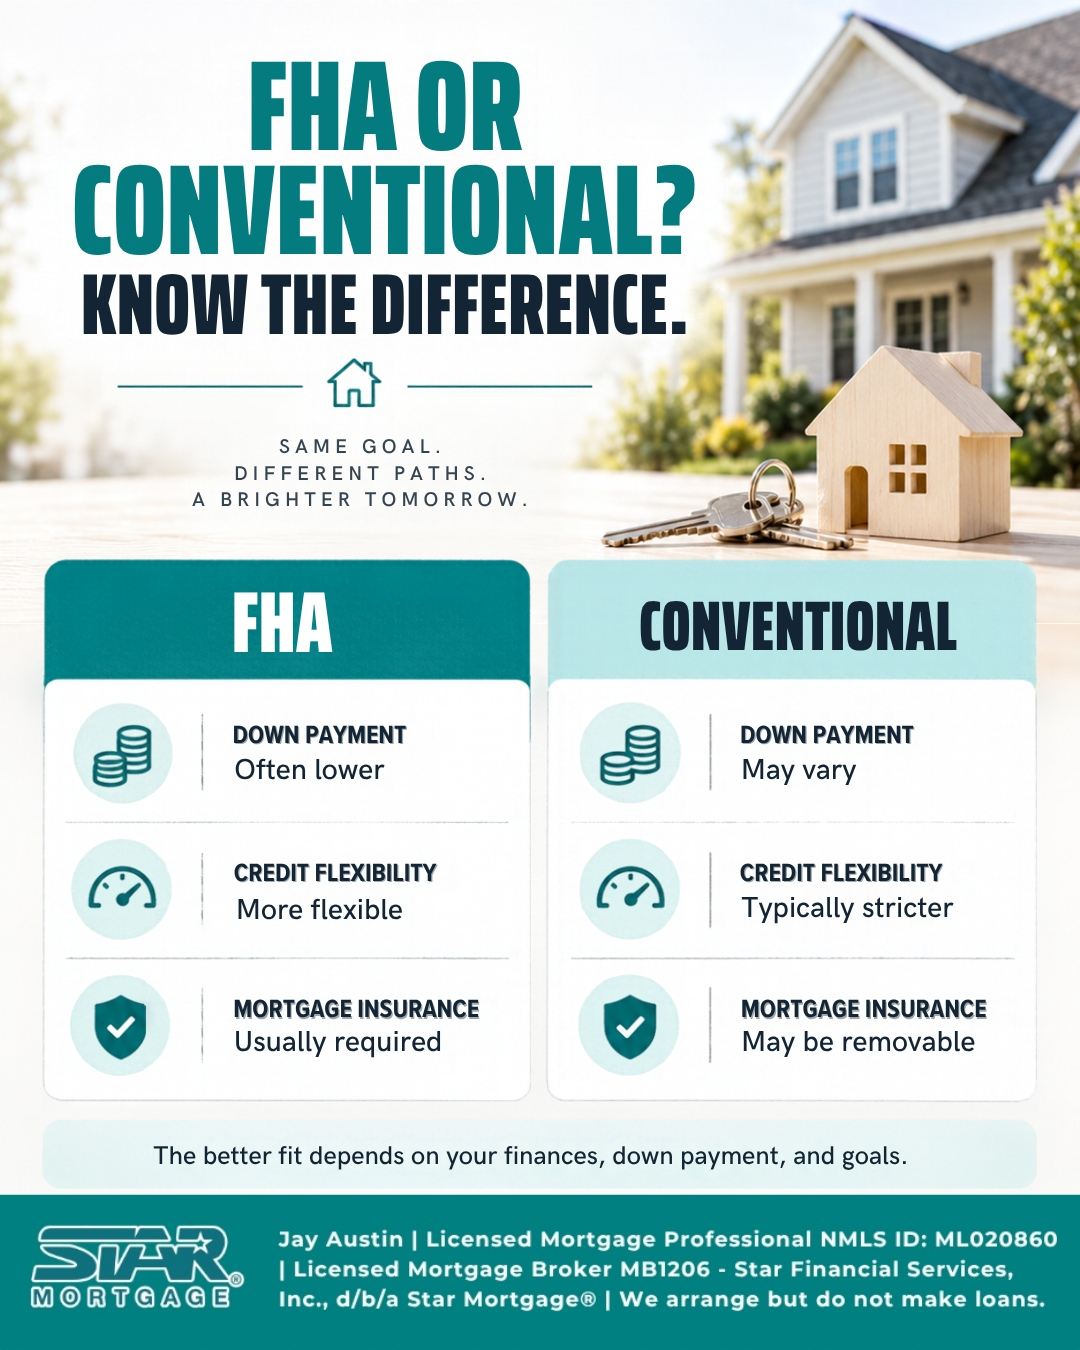
Let’s start with FHA loans. These loans are designed to help first-time homebuyers and those with less-than-perfect credit. One of the biggest advantages of FHA loans is the lower down payment requirement, which can be as low as 3.5%. This can be a huge benefit for buyers who may struggle to save a large sum for a down payment. Additionally, FHA loans tend to be more forgiving when it comes to credit scores. If your score is around 580 or higher, you may qualify for an FHA loan.
Another noteworthy feature of FHA loans is that they allow for higher debt-to-income ratios. This means that you can have more debt compared to your income while still being eligible for a loan. If you have student loans, credit card debt, or other financial obligations, this could make it easier for you to qualify for a mortgage.
However, FHA loans do come with costs that you need to be aware of. One key consideration is mortgage insurance. FHA loans require borrowers to pay both an upfront premium and monthly premiums for mortgage insurance, which protects the lender in case of default. This can add to your monthly expenses, so it's essential to factor this into your budget.
Now, let's discuss conventional loans. These loans are not backed by the government and typically require a higher credit score than FHA loans. Generally, you may need a score of 620 or above to qualify. While this might seem like a hurdle for some, those with good credit might find that conventional loans offer greater flexibility and potentially fewer overall costs.
One of the major advantages of conventional loans is that they do not require mortgage insurance if you can make a down payment of 20% or more. This can lead to significant savings over the life of the loan. Furthermore, conventional loans often have lower total loan costs, especially for borrowers with strong credit profiles.
Conventional loans also come with a variety of terms. You can choose from different loan lengths, such as 15 or 30 years, and you may have the option to select a fixed or adjustable interest rate. This flexibility can allow you to tailor your mortgage to fit your specific financial situation.
When comparing FHA and conventional loans, it’s essential to consider your financial situation. For example, if you have a low credit score or are unable to make a large down payment, an FHA loan may be a more suitable choice. On the other hand, if you have a strong credit score and can put down 20% or more, a conventional loan might save you money in the long run.
It’s also worth noting that the property type can influence your decision. FHA loans have specific requirements regarding the condition of the home, which means that they may not be suitable for all properties. If you’re considering buying a fixer-upper or a home that may not meet strict FHA guidelines, a conventional loan could offer you more flexibility.
Another factor to keep in mind is the length of time you plan to stay in the home. If you anticipate moving within a few years, the lower down payment on an FHA loan may help you get into a house sooner. However, if you plan to stay long-term, a conventional loan might be the better option due to the potential savings from avoiding mortgage insurance.
In addition to these factors, it’s essential to evaluate how much you can afford. A thorough budget analysis can help you understand how much you can allocate for a monthly mortgage payment. When reviewing your budget, consider not just the loan payment itself, but also property taxes, homeowners insurance, and any potential homeowners association (HOA) fees.
As you gather information, it’s a good idea to think about your overall financial picture. Are you planning for other major expenses, such as education costs or retirement savings? Your mortgage should fit into your broader financial goals, and it’s crucial to choose a loan that aligns with your future plans.
If you’re still unsure about which option is best for you, reaching out for a personalized consultation can provide valuable insights. A Licensed Mortgage loan Advisor can help you evaluate your specific needs, discuss your financial situation in detail, and answer any questions you may have about both FHA and conventional loans.
Taking the time to explore both options will equip you with the knowledge you need to make an informed decision about your home financing. Whether it's understanding the impact of mortgage insurance, the importance of credit scores, or the nuances of different loan products, educating yourself will pave the way to a successful home buying experience.
Remember, your goals are the priority. The right mortgage can facilitate your journey to homeownership, support your financial stability, and align with your future plans. So, take the next step and reach out to discuss your specific needs and objectives. Your dream home could be just around the corner!
As you think about embarking on your home search, remember that you're not alone with a Star Mortgage Licensed Professional. The world of mortgages can be complicated, but with the right preparation and guidance, you can set yourself up for success. Don’t hesitate to reach out to discuss your specific needs and situation. It’s an exciting time, and being proactive about your finances can help you achieve your homeownership goals!
We are here to help!
Learn about Loan Programs that can lower your monthly payment, making your home purchase more affordable.
Just let us know when it is a good time for you, or TEXT 508 941-5616 to book a time convenient for you. We can then chat about how we can help. After we have had the opportunity to speak, I promise you will have a clearer understanding of what it will take to buy your dream home.
Get pre-approved quickly with our SECURE ONLINE Loan Application. It's Quick and Easy and available 24 hours a day - 7 days a week.
Click here: Why the Right Pre-Approval Letter Matters When You Make an Offer to Purchase - Star Mortgage
Sound Advice Topics Sponsored by StarMortgage.com
Now go back to Our Blog Home Page to learn more about all about financing a home Blog - Star Mortgage