How you can make your initial monthly payment more affordable
When you are planning to buy a home, the Monthly Payment can be just as important as the Purchase Price. A lower starting payment may give you more room in your budget, help you qualify for a home that fits your needs, or make it easier to manage other expenses. One option to consider is an FHA 5/1 adjustable-rate mortgage, often called an FHA 5/1 ARM.
This type of loan may offer a lower initial interest rate than some fixed-rate loans. In return, the rate can change later, which means your payment may rise or fall. Understanding how the loan works, what can affect your payment, and how long you expect to keep the home can help you decide whether it fits your plans.
What are the potential benefits for the First Time Buyer?
How an FHA 5/1 ARM works
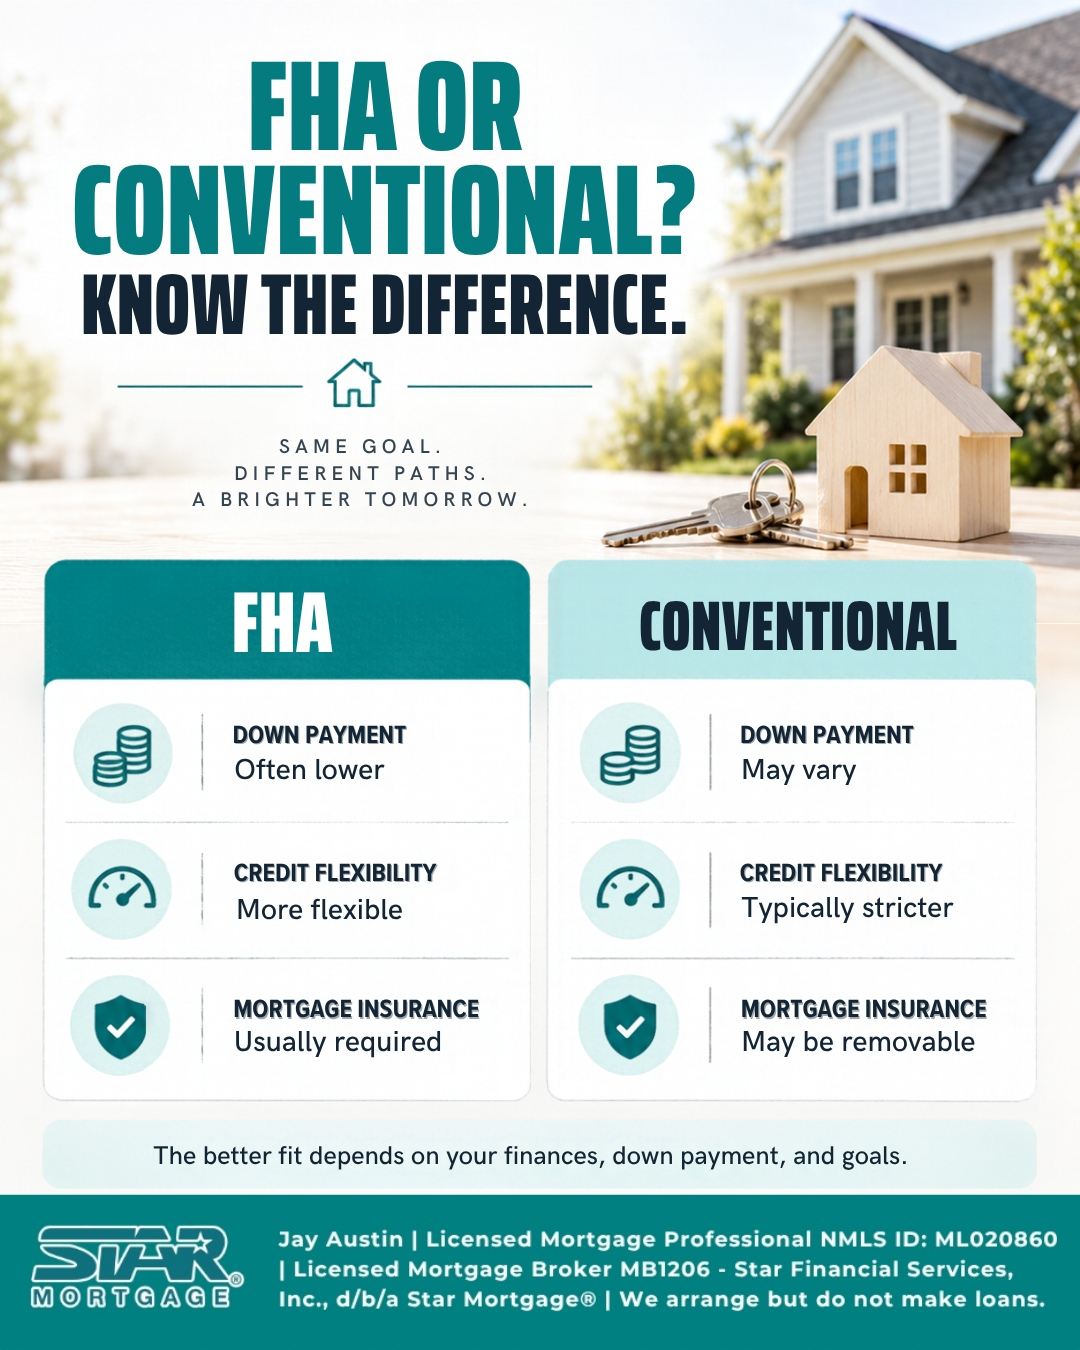
An FHA 5/1 ARM is a mortgage insured by the Federal Housing Administration. The FHA does not lend you the money. Instead, its insurance helps protect the lender if a borrower does not repay the loan. That insurance can make FHA financing available to some buyers who may not meet the requirements for other types of loans.
The “5/1” describes how the interest rate works. The rate is generally fixed for the first five years. After that initial period, it can adjust once each year. The loan documents spell out when the first adjustment may happen and how often later adjustments can occur.
During the fixed-rate period, your principal and interest payment generally stays the same, as long as you do not change the loan through a refinance or other action. Once the rate begins to adjust, the payment may change. Your total monthly housing cost may also include property taxes, homeowners' insurance, and mortgage insurance, and those costs can change independently of the interest rate.
A lower starting payment can help with affordability
Because the initial rate on an ARM may be lower than the rate on a comparable fixed-rate loan, the starting principal and interest payment may be lower too. That difference can matter when you are working within a set monthly budget.
For example, a lower payment could leave more room for utilities, repairs, childcare, savings, or other household costs. It may also make it easier to consider homes that would otherwise feel out of reach. But it is important to view the lower starting payment as one part of the full picture, not a guarantee that the loan will remain affordable over time.
The payment after the initial period depends on the loan’s adjustment terms and the index used to calculate future rates. If the index rises, your interest rate and payment may rise, subject to the loan’s limits. If it falls, your rate may decrease, though the loan terms may set a minimum rate. Your lender can help you review the payment limits and see how different adjustment scenarios could affect your budget.
Know more details about the adjustment terms
Every ARM has terms that explain how its rate can change. A key term is the index, which is a published measure used to help determine the new rate. The loan also has a margin, which is added to the index when the rate adjusts. The index can move over time, while the margin is set in the loan terms.
You should also understand the adjustment caps. These limit how much the rate can increase or decrease at certain points. A loan may have a cap on the first adjustment, a cap on each later adjustment, and a lifetime cap that limits the highest possible rate over the life of the loan. The exact caps can vary, so review the terms for the loan you are considering.
Explore the FHA 5/1 ARM offered by www.StarMortgage.com
Here is an overview of hoe the FHA 5/1 Adjustable-Rate Mortgage works
Its interest rate stays the same for the first five years, then it will adjust one a year thereafter.
Rate caps limit how much the rate can change, but the limits depend on your loan terms. Compare the initial rate and possible future payments to see whether this loan type fits your budget.
Please feel free to contact me for details and get a current quote of the current starting rate, your estimated loan amount, and more information about the specific cap structure, we can prepare an estimate of what to expect your payment will be and its maximum rate increase.
FHA 5-year ARM "HUD says the rate stays fixed for five years and then adjusts annually. The allowed cap structures can be either 1 percentage point per year and 5 points over the loan’s life, or 2 points per year and 6 points over the loan’s life. Your loan documents must specify which applies. After the fixed period, the adjusted rate is generally based on an index plus the lender’s margin, subject to the caps."
Be sure to ask for an explanation of the highest possible payment under the loan’s terms. Also ask when the first adjustment could occur, what index is used, how the margin works, and how often the rate can change. Looking at both the starting payment and possible future payments can help you make a more informed decision.
Consider how long you may keep the home
An FHA 5/1 ARM may be worth considering if you expect to sell the home, pay off the mortgage or refinance before the first interest rate adjustment. For example, a planned move, a change in household needs, or a short-term job assignment may affect how long you expect to stay. Still, plans can change. A job opportunity may fall through, a move may be delayed, or you may decide you want to stay longer than expected.
It can be risky to assume that you will be able to refinance before the rate changes. Refinancing later depends on your income, credit, home value, loan balance, and the loan options available at that time. Those conditions may not be the same as they are when you buy. It is best to consider whether you could manage the payment if you kept the home and the rate adjusted upward.
Compare the ARM with a fixed-rate loan
A fixed-rate mortgage has an interest rate that generally stays the same for the life of the loan. That can make principal and interest payments easier to plan for. An FHA 5/1 ARM may have a lower starting payment, but it carries the risk of payment changes after the fixed period.
When comparing these choices, look beyond the first monthly payment. Consider the estimated payment at the start, the possible payment after the first adjustment, and the maximum payment allowed by the loan terms. Also consider how each option fits your expected time in the home and your comfort with uncertainty.
Your total monthly housing cost matters too. FHA loans generally require mortgage insurance, and the cost and duration depend on the loan terms and other factors. Property taxes and homeowners insurance are separate costs that may rise over time. If the home is part of a community with association fees, include those as well. A payment that looks manageable when you count only principal and interest may feel different once all housing costs are included.
Check whether FHA financing fits your situation
FHA loans have program rules, including requirements related to the home, the loan amount, and the borrower’s ability to repay. The home must meet applicable FHA property standards, and the loan must fall within the relevant loan limits for the area. Your credit, income, debts, down payment, and other details may affect whether you qualify and what terms are available.
FHA mortgage insurance is an important part of the cost. It often includes an upfront mortgage insurance premium and an annual premium paid over time, typically as part of the monthly payment. The amount and duration can depend on factors such as the loan size, down payment, and loan term. Be sure to review these costs when you estimate affordability.
Ways to prepare before choosing
If you have specific questions or need personalized guidance tailored to your financial situation, I invite you to reach out and speak with a Star Mortgage Licensed Mortgage Professional. They will provide Sound Advice and be there as your valuable advisor throughout the entire process of purchasing or refinancing a home. Together, we can navigate the complexities of the mortgage process and help you achieve your homeownership dreams.
Call 508 941-5616 to speak with a Licensed Mortgage Professional. If you are in the beginning stages of planning to purchase a home or just need some sound advice, just give us a call 508 941-5616 text or email Advice@StarMortgage.com
Looking forward to speaking with you real soon! I am here to Help make those very important decisions with sound advice.
What Our Clients Say about their experience with Star Mortgage. Check out our reviews at Star Mortgage Customer Reviews Check us out, you will be glad you did!
See What Our Customers Say about Star Mortgage
https://www.starmortgage.com/our-reviews
Ready to get started? Quickly Connect with us online to qualify for your FREE Consultation and Pre-Qualification Letter.
Get pre-approved quickly with our SECURE ONLINE Loan Application. It's Quick and Easy and available 24 hours a day - 7 days a week.
Click here: Why the Right Pre-Approval Letter Matters When You Make an Offer to Purchase - Star Mortgage
Sound Advice Topics Sponsored by StarMortgage.com
Go back to Our Blog Home Page to learn more about all about financing a home Blog - Star Mortgage
📞 Call or text 508-941-5616 to schedule your FREE 30–45 minute consultation and review all your home-buying options.
🏡 Learn more about how we can make it easier to purchase a home:https://www.starmortgage.com/easy-purchase
* Specific loan program availability and requirements may vary. Please get in touch with your mortgage advisor for more information.